
Retirement planning conversations usually start with a number: how much you’ve saved, how much you’ll need, how long it has to last. But there’s a quieter variable that gets less attention and can quietly reshape that math, and that’s where you actually live once the paychecks stop.
Curious how an AI model would sort through the tangle of state tax codes, I asked ChatGPT to name the ten best states for retirement taxes. Some answers were predictable. A few were not, especially once income tax states with generous retirement exemptions entered the mix alongside the usual no-tax suspects.
Wyoming
Wyoming (Image Credits: Pexels)
Wyoming keeps showing up at the top of retirement tax rankings, and the reasoning holds up under scrutiny. Wyoming is the best state for retirement, in large part due to affordability reasons, with a cost of living adjusted for retirees' needs that falls in the more affordable half of the nation. That affordability pairs with a tax structure built around avoiding big levies altogether.
The state is considered highly friendly to retired taxpayers, offering the added benefit of no estate or inheritance tax. On top of that, Wyoming boasts the third-lowest general tax burden according to WalletHub's taxpayer ranking, which tracks costs across property, sales, and income taxes combined. For retirees drawing pensions, Social Security, and 401(k) withdrawals from multiple sources, that combination is hard to beat.
Florida
Florida (Image Credits: Pexels)
Florida's reputation as a retirement magnet isn't just about beaches and sunshine, though those help. Florida ranks as the second-best state to retire due to its relatively low taxes for retired people, including no estate, inheritance or income taxes. That trio of eliminated levies is exactly what most retirees list as their biggest financial worry.
The state also backs up its tax policy with real support for older residents. Florida receives more funding per senior from the Older Americans Act than all but two other states, which funds things like transportation, homemaker assistance and nutrition programs for seniors. Housing costs run higher than in some competitors, but for retirees prioritizing tax efficiency over rock-bottom living expenses, Florida still lands near the top of most lists.
Nevada
Nevada (Image Credits: Pexels)
Nevada rarely gets the same spotlight as Florida, yet its tax treatment of retirees is arguably just as strong. The state belongs to the small group of states in which individual income is not subject to tax: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, and Wyoming. That means Social Security, pensions, and retirement account withdrawals all pass through untouched at the state level.
Nevada also skips the estate and inheritance taxes that can erode wealth passed to heirs. Combined with no income tax, that makes long-term legacy planning notably simpler for retirees who want to leave something behind without a state tax bill attached to it.
South Dakota
South Dakota (Image Credits: Pexels)
South Dakota tends to surprise people who assume tax-friendly states are all coastal or sunbelt destinations. South Dakota is the third-best state for retirees, offering taxpayer-friendly conditions with no estate or inheritance taxes. Its income tax structure doesn't exist at all, which puts it firmly in the no-income-tax club alongside Wyoming and Florida.
Beyond taxes, the state pairs affordability with unusually strong healthcare access for its size. South Dakota has one of the lowest rates of social isolation for seniors, and it boasts the second-best geriatrics hospitals in the country. For retirees weighing tax savings against quality-of-life factors, South Dakota manages to check both boxes at once.
Alaska
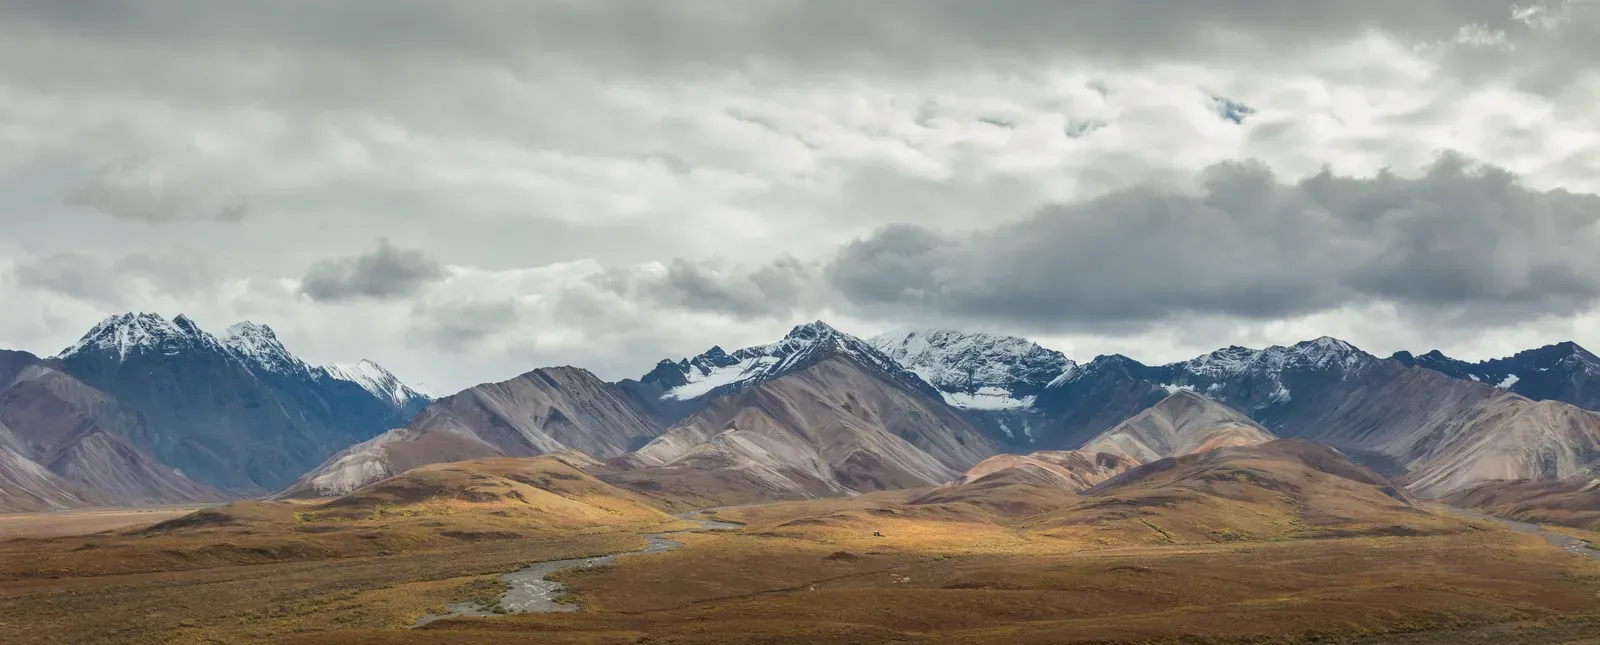
Alaska (By Diego Delso, <a href="https://commons.wikimedia.org/w/index.php?curid=69586521" target="_blank" rel="noopener">CC BY-SA 4.0</a>)
Alaska often gets overlooked in retirement conversations, partly because of its climate reputation, but its tax profile is genuinely exceptional. The most tax-friendly state for retirees is Alaska, where there's no income tax and no state sales tax, no estate tax and no inheritance tax. That's four major tax categories eliminated in one state, which is rare even among the no-income-tax group.
Some Alaska residents even receive an annual dividend from the state's oil revenue fund, adding a small but real income stream rather than just tax relief. For retirees willing to trade warmer winters for a genuinely light tax burden, Alaska deserves more attention than it usually gets in these rankings.
Tennessee
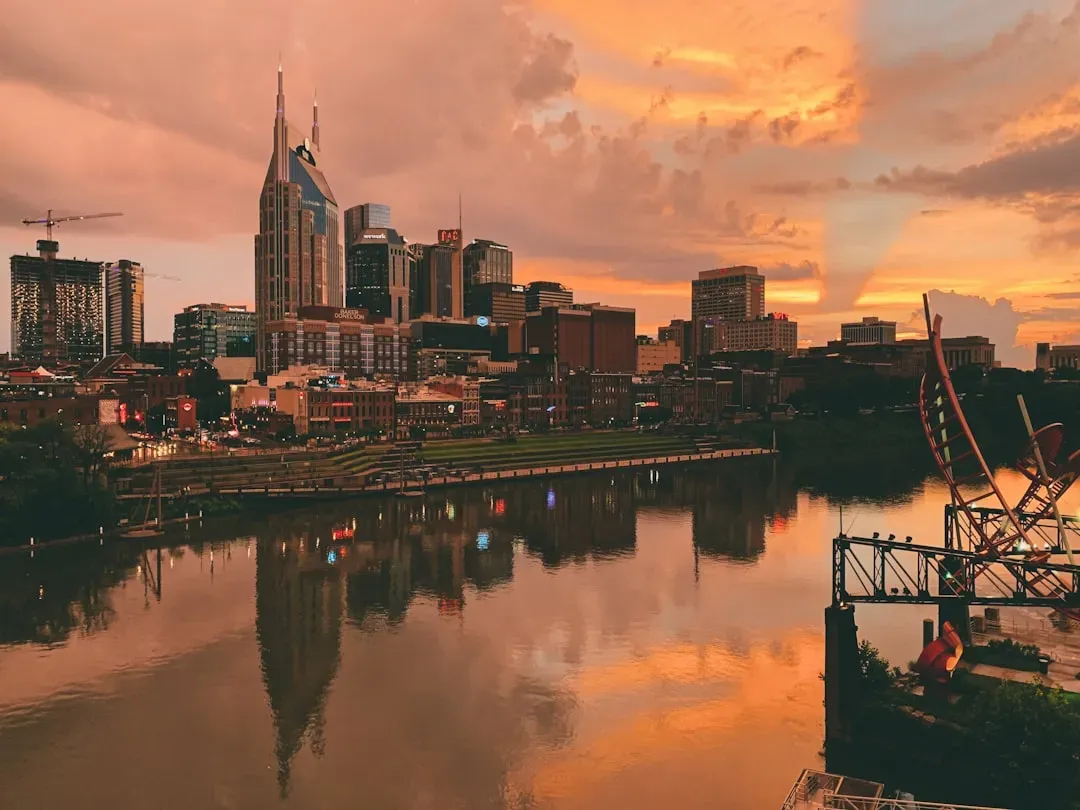
Tennessee (Image Credits: Unsplash)
Tennessee combines tax-friendliness with a lower overall cost of living than many of its no-income-tax peers. Tennessee's tax structure is among the most retiree-friendly in the country, with no state income tax, so Social Security benefits and retirement income go untouched, and low property taxes help stretch savings even further. That property tax advantage matters, since some no-income-tax states offset the savings with steeper property bills.
Day-to-day expenses also stay manageable. Tennessee has one of the lowest costs of living in the United States, at 10% below the national average. Housing options range widely, and cities like Nashville and Chattanooga offer senior care facilities that hold up well against national benchmarks.
New Hampshire
New Hampshire (Image Credits: Unsplash)
New Hampshire has quietly become more attractive to retirees over the past couple of years. It has always sat among the states with no broad income tax, but until recently it still taxed interest and dividend income, a detail that mattered to retirees living off investment portfolios. New Hampshire recently eliminated its tax on dividend and interest income as of tax year 2025.
That change closed the last real gap in the state's retirement tax appeal. Now Social Security, pensions, and retirement account distributions all pass through free of state income tax, with no lingering carve-out for investment income either. The tradeoff is New Hampshire's property taxes, which run higher than the national average, so the full picture depends on housing choices within the state.
Illinois
Illinois (Image Credits: Pexels)
Illinois is the entry that tends to catch people off guard, since the state has a reputation for higher taxes overall. The nuance is that its income tax barely touches retirees at all. Illinois has a 4.95% income tax on wages, but a retiree drawing entirely from Social Security, a pension, and IRA distributions pays 0% state income tax.
That exemption covers essentially every common retirement income stream. All retirement income, including pensions, Social Security, and IRA and 401(k) distributions, is exempt from Illinois state income tax, one of the most generous retirement tax policies in the country. For retirees who already have family or ties in the Midwest and assumed Illinois was off the table for tax reasons, this exemption often changes the calculation.
Pennsylvania
Pennsylvania (Image Credits: Unsplash)
Pennsylvania follows a similar pattern to Illinois, using a flat income tax rate but carving out an unusually generous exemption for retirees. The Pennsylvania Department of Revenue exempts all retirement income after age 59 1/2 under its 3.07% flat tax. That age threshold matters for anyone considering early retirement, since income drawn before that point doesn't get the same treatment.
The state's appeal extends beyond its own residents, too. Pennsylvania is particularly popular with retirees from neighboring high-tax states like New York and New Jersey. For retirees along the East Coast corridor who want to stay reasonably close to family without absorbing a heavy state tax bill, Pennsylvania offers a practical middle ground.
Mississippi
Mississippi (Image Credits: Pexels)
Mississippi rounds out the list as another income tax state that treats retirees far more gently than its headline rate suggests. Most retirement income, including Social Security and pension payments, passes through exempt, while other income is taxed at a comparatively low rate. The tax on taxable income is a flat 4% rate for 2026 on taxable income exceeding $10,000.
That rate is also on a downward path. The tax rate is set to be reduced gradually to 3% by 2030, with further decreases until the tax is eliminated entirely, with the rate falling to 4% in 2026. Combined with a low overall cost of living, Mississippi ends up as one of the more affordable, tax-light options for retirees willing to look past its usual reputation.
What the ChatGPT list gets right, and where it needs context
What the ChatGPT list gets right, and where it needs context (Image Credits: Unsplash)
The pattern across these ten states splits cleanly into two groups. Half have no state income tax at all, while the other half tax wages generally but carve out near-total exemptions for retirement income specifically, which is exactly the kind of nuance a quick internet search might miss. As of 2026, there are just eight states that tax Social Security: Colorado, Connecticut, Minnesota, Montana, New Mexico, Rhode Island, Utah and Vermont, meaning the vast majority of states, including several not on this list, already leave Social Security alone.
Income tax is only one piece of the puzzle, though. The federal estate tax exemption has increased over the years to $15 million in 2026, up from $13.99 million in 2025, which matters less for most retirees than state-level estate rules, property tax rates, and sales tax exemptions on groceries and medicine. A state with zero income tax but steep property taxes can end up costing a retiree more than an income tax state with a strong retirement exemption, so the full picture always requires checking more than one column.
Final thoughts
Final thoughts (Image Credits: Unsplash)
Asking an AI model to rank tax-friendly retirement states produced a useful shortlist, but the real value is in the reasoning behind each entry rather than the ranking itself. No income tax states like Wyoming, Florida, Nevada, South Dakota, Alaska, and Tennessee remain reliable choices for straightforward tax relief, while Illinois, Pennsylvania, Mississippi, and New Hampshire prove that a state's headline tax rate doesn't always reflect what retirees actually pay.
For anyone weighing a move, the smarter approach is to run the full picture, income tax, property tax, sales tax, and estate rules together, against personal income sources rather than relying on a single ranking. Tax codes shift every year, and a state that looks ordinary today could easily earn a spot on next year's list.