
Money fights rank among the most common reasons couples argue, yet some partnerships seem to sidestep the tension almost entirely. Financial advisors who work with couples on a regular basis notice patterns among the ones who handle shared finances with relatively little friction. It’s rarely about income level or even financial knowledge. Instead, it tends to come down to a handful of repeatable habits that keep money conversations calm and productive.
These habits aren’t complicated or expensive to adopt, but they do require consistency. Below are six behaviors that financial professionals frequently point to when describing couples who seem to have their financial life together.
1. They schedule regular money check-ins
1. They schedule regular money check-ins (Image Credits: Unsplash)
Couples who avoid financial blowups tend to talk about money on a set schedule rather than only when something goes wrong. This might look like a fifteen minute conversation every Sunday evening or a longer monthly review of bank statements and upcoming expenses. The point isn’t to make it formal or stressful, it’s to normalize the conversation so it doesn’t feel loaded every time it comes up.
Advisors often note that couples who skip these check-ins tend to only discuss money during a crisis, like an unexpected bill or a credit card statement that’s higher than expected. That reactive pattern breeds resentment because one partner ends up feeling blindsided while the other feels attacked. A predictable rhythm removes a lot of that emotional charge.
2. They agree on shared goals before making a budget
2. They agree on shared goals before making a budget (Image Credits: Unsplash)
Successful money management as a couple usually starts with agreeing on what the money is actually for, not just how much is coming in and going out. Couples who are aligned tend to talk through goals like buying a home, paying off debt, or retiring at a certain age before they ever build a spreadsheet. The budget becomes a tool to reach the goal rather than a restrictive exercise that feels arbitrary.
Without that shared vision, a budget can feel like one partner imposing rules on the other. Financial advisors frequently point out that arguments about spending are often really disagreements about priorities that were never explicitly discussed. Getting the goals settled first tends to make the numbers conversation much easier.
3. They keep some financial transparency, even with separate accounts
3. They keep some financial transparency, even with separate accounts (Image Credits: Pexels)
Not every couple combines all their money into one joint account, and advisors generally agree that isn’t necessary for financial harmony. What matters more is that both partners can see the full financial picture when they need to. Some couples keep individual accounts alongside a shared one for bills and joint goals, which can reduce friction over personal spending while still keeping shared obligations visible.
The habit that actually protects the relationship is the willingness to be upfront about debt, income changes, or big purchases before they happen. Secrecy, even around small amounts, tends to erode trust faster than the money itself ever could. Couples who manage money well simply don’t let financial surprises pile up unspoken.
4. They divide financial tasks based on strengths, not default assumptions
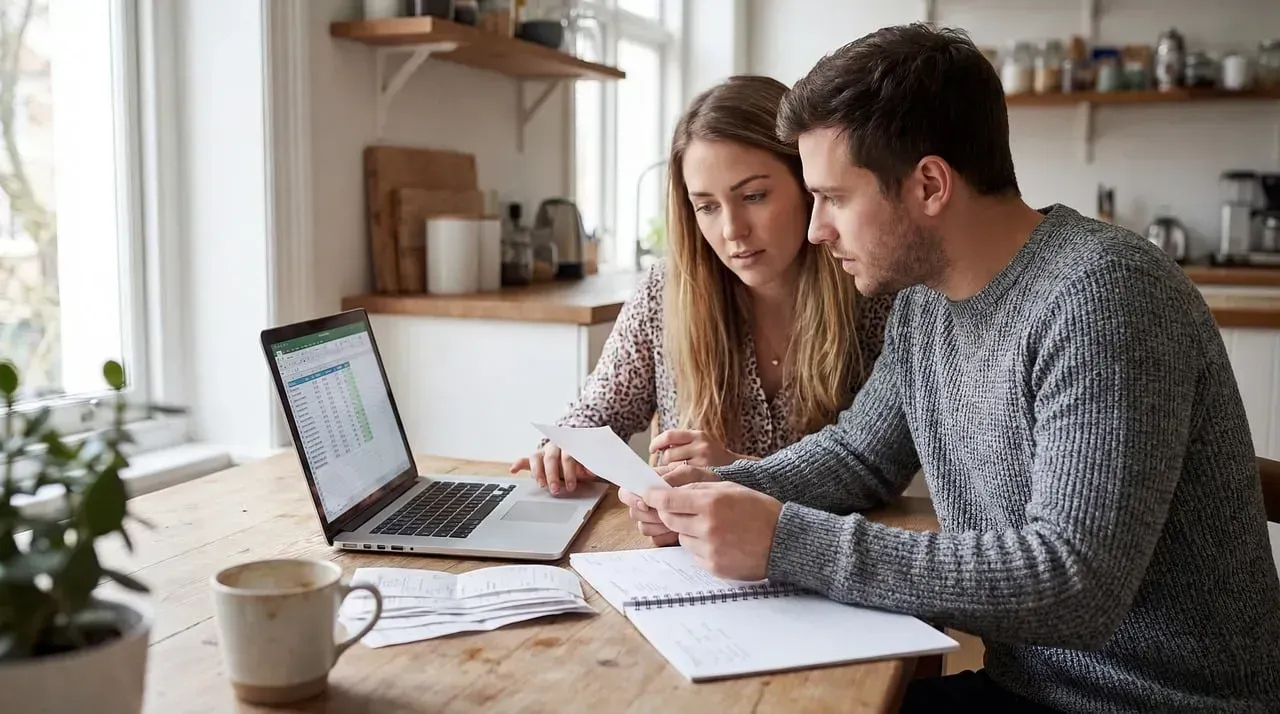
4. They divide financial tasks based on strengths, not default assumptions (Image Credits: Pixabay)
In many households, one person ends up paying all the bills and tracking the accounts simply because they did it once and it stuck. Couples who handle money well tend to be more deliberate, dividing responsibilities based on who is actually good at or interested in a given task. One partner might handle day to day bill paying while the other manages investments or tax planning, for example.
This division works best when both partners still stay informed about the whole picture rather than checking out entirely from tasks they didn’t take on. Advisors sometimes see trouble when one partner handles everything financial and the other has little idea what accounts exist or what debts are owed. A clear division of labor works only when it comes with shared visibility.
5. They build an agreed upon buffer for individual spending
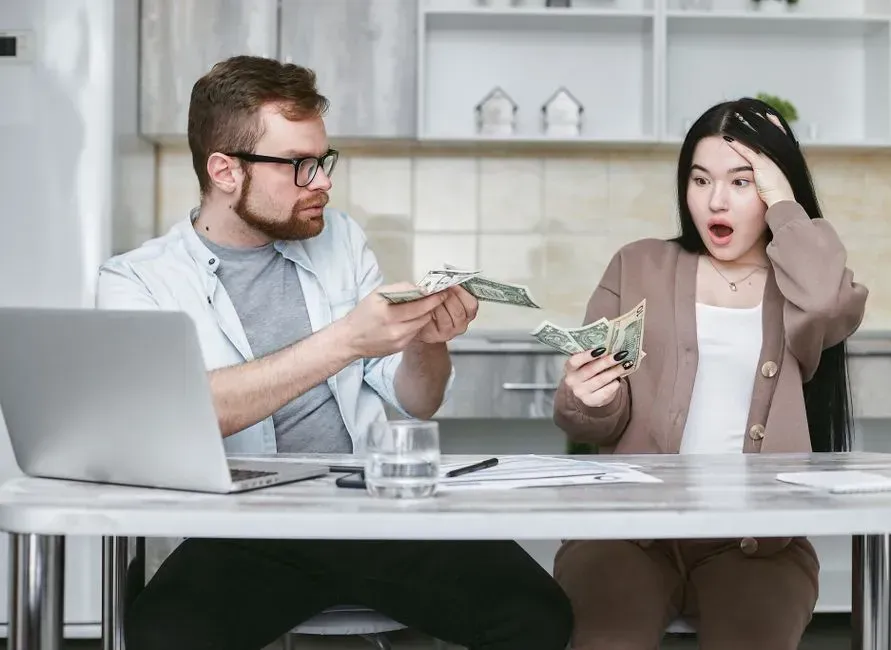
5. They build an agreed upon buffer for individual spending (Image Credits: Pexels)
Money arguments often start over small, recurring purchases rather than big ticket items, things like coffee, hobbies, or subscriptions. Couples who avoid this friction tend to set aside a personal spending allowance that each partner can use without needing to explain or justify it. The amount matters less than the fact that it exists and both people agreed to it.
This habit gives each partner a small sense of financial independence inside a shared financial life. It also removes the need for a conversation every time someone wants to buy something minor, which advisors say reduces the day to day nagging that can wear down a relationship over time. The buffer becomes a pressure release valve rather than a loophole.
6. They revisit and adjust their financial plan as life changes
6. They revisit and adjust their financial plan as life changes (Image Credits: Pexels)
A financial plan that made sense five years ago rarely fits perfectly today, and couples who manage money well tend to treat their plan as something that evolves. Job changes, new children, inheritances, or shifts in health can all reshape what a household needs from its finances. Rather than sticking rigidly to an old budget or investment strategy, these couples revisit the plan when circumstances shift.
This doesn’t mean constant overhauls, but it does mean checking in during major life transitions rather than assuming the old plan still applies. Advisors often see couples struggle when they treat an early financial agreement as permanent even after their income, family size, or goals have changed substantially. Flexibility built into the process from the start tends to make those adjustments feel routine instead of disruptive.
None of these habits require a background in finance or a particular income bracket. They’re built on communication patterns that couples choose to practice consistently, which is often the harder part. Small, repeated behaviors like these tend to matter more over time than any single big financial decision.