Every investor eventually faces the same core question: how much risk am I actually willing to take? The answer shapes everything, from which accounts you open to how you react when markets drop fifteen percent in a month. Knowing where different strategies fall on the risk spectrum is genuinely useful, whether you’re building a portfolio from scratch or reassessing one that’s been running on autopilot.
The nine approaches below are ordered from the most conservative to the most aggressive. They’re not mutually exclusive. Most people blend two or three of them depending on time horizon, life stage, and honest self-assessment of how they’ll behave when things get uncomfortable.
1. High-Yield Savings Accounts and Money Market Accounts
1. High-Yield Savings Accounts and Money Market Accounts (Image Credits: Unsplash)
A high-yield savings account is completely safe in the sense that you’ll never lose money. Most accounts are government-insured up to $250,000 per account type per bank, so you’ll be compensated if the financial institution fails. This makes them the closest thing to a no-risk investment that still earns something. They’re best suited for emergency funds or cash you might need within the next year or two.
While high-yield savings accounts are considered safe investments, you run the risk of losing purchasing power over time due to inflation. That will happen if the interest rate paid on the account is lower than inflation, which was running at about 3% in September 2025. The trade-off is simplicity and total capital preservation, which for many people in uncertain markets is worth the modest yield. With fewer overhead costs, you can typically earn much higher interest rates at online banks than you would at a traditional brick-and-mortar bank.
2. Money Market Funds
2. Money Market Funds (Image Credits: Pixabay)
Money market funds are a type of mutual fund that invests in low-risk, short-term debt securities, such as Treasury bills, municipal debt, or corporate bonds. They’re designed to offer a safe, stable investment option for money you may need to access in the short term, like an emergency fund or a short-term goal. Unlike a standard savings account, they sit inside your brokerage account and earn income from a diversified pool of short-term instruments.
Government money market funds invest only in assets backed by the federal government, for example Treasury bonds. Because of this government backing, they’re considered the safest and most liquid type of money market fund. Money market funds come with very low risk, but there have been rare instances where funds “broke the buck,” meaning their NAV dropped below $1, such as during the 2008 financial crisis. When that happens, the fund may be liquidated and investors could receive less than $1 per share. It’s a remote scenario, but worth knowing.
3. U.S. Treasury Securities and TIPS
3. U.S. Treasury Securities and TIPS (Image Credits: Pexels)
The U.S. Treasury issues Treasury bills, Treasury notes, Treasury bonds and Treasury inflation-protected securities, or TIPS: Treasury bills mature in one year or sooner. Treasury notes stretch out up to 10 years. Treasury bonds mature in up to 30 years. If you keep Treasurys until they mature, you generally won’t lose any money, unless you buy a negative-yielding bond. If you sell them sooner than maturity, you could lose some of your principal, since the value will fluctuate as interest rates rise and fall.
TIPS are issued by the United States Treasury, making them virtually risk-free. The principal increases with inflation, ensuring your investment still retains its purchasing power. TIPS offer steady returns without major price swings. After the prolonged period of very low rates that followed the Global Financial Crisis, U.S. Treasury rates are now approximately at “fair value” and could present an attractive entry point. Those relatively high starting yields can add to bonds’ total returns and help provide a cushion against interest rate volatility.
4. Investment-Grade Corporate Bonds
4. Investment-Grade Corporate Bonds (Image Credits: Unsplash)
Corporate bonds offer a higher yield compared to government bonds, making them an appealing option for those willing to take on a bit more risk. In 2025, the corporate bond market presents two main categories worth considering: investment-grade corporate bonds and high-yield corporate bonds. Investment-grade bonds, issued by financially stable companies with strong credit ratings, sit clearly on the safer side of that divide.
Bonds from blue-chip companies with high credit ratings and a history of stable earnings are generally good choices. Investors should also look for bonds with attractive yields compared to their risk profiles and consider diversifying across sectors to mitigate risk. Solid returns in fixed income markets in 2026 are expected, driven by central bank rate cuts in response to a weakening labor market. However, the bulk of returns will likely come from coupon income rather than price appreciation, as resilient economic growth and persistent inflation pressures may limit the drop in yields.
5. Dividend Stocks and REITs
5. Dividend Stocks and REITs (Image Credits: Unsplash)
REITs and dividend stocks provide income but can fluctuate with market conditions. That single sentence captures the transition we make here: stepping into equities means accepting real market risk in exchange for a more meaningful return potential. REITs typically pay high dividends because they’re required to disburse at least 90% of their taxable income. For income-focused investors, that mandatory payout structure has a certain appeal.
Procter and Gamble has been paying dividends for 135 years and increasing its payout for 69 consecutive years, and it had an above-average 2.7% yield as of March 2026. That’s one of the best dividend histories in the entire stock market. Whether through direct ownership or via REITs, real estate often acts as a hedge against inflation and market volatility. Investing in real estate offers numerous benefits, including steady rental income, tax advantages, and long-term appreciation potential. Unlike stocks, real estate often retains value during economic downturns, making it a reliable asset class.
6. Broad Market Index Funds
6. Broad Market Index Funds (Image Credits: Pexels)
The best index funds can help you build wealth by diversifying your portfolio while keeping fees low. Unlike investing in individual stocks or bonds, index funds spread your risk across hundreds of securities, meaning your returns aren’t tied to the fate of any single company. This is the approach most widely recommended for long-term investors who don’t want to pick individual stocks but still want meaningful equity exposure.
On average, most investors do not outperform the market, so a straightforward approach like owning index funds often makes the most sense. For everyday investors, low-cost index funds offer a smart and accessible way to grow wealth steadily without needing deep expertise in stock-picking. What shows persistent explanatory power is cost, specifically a fund’s expense ratio. The expense ratio is the annual fee charged by a fund, expressed as a percentage of assets under management. Keeping that number low has a compounding effect on long-term returns that’s easy to underestimate.
7. Growth Stocks and Sector-Focused Funds
7. Growth Stocks and Sector-Focused Funds (Image Credits: Pexels)
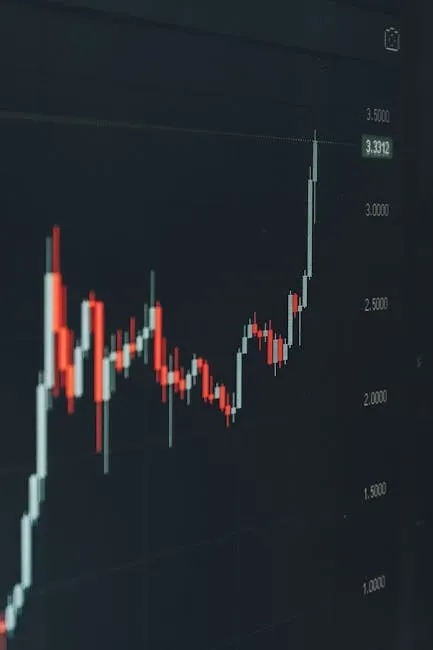
Equities extended their bull run in 2025, but valuations remain historically stretched amid a sharp dispersion of returns across sectors. Investing in growth stocks or concentrated sector funds, such as technology or artificial intelligence, offers the potential for outsize gains but demands the stomach for sharp drawdowns. These are not passive, set-and-forget strategies.
2026 is characterized by above-trend economic growth, easing policy, and accelerating productivity. This backdrop favors risk taking, but weakness in the labor market, rich valuations, and an uncertain forward path for interest rates remain risks, arguing for greater selectivity. Artificial Intelligence remains the dominant theme for investors, as it catalyzes a capital-intensive expansion, boosting productivity and sustaining earnings strength. Investors drawn to AI and tech must weigh that narrative against valuations that remain near historical peaks.
8. Small-Cap Stocks
8. Small-Cap Stocks (Image Credits: Unsplash)
Small-cap companies typically have market caps between $300 million and $2 billion, and are often younger, faster-growing businesses. These funds offer four key advantages: portfolio diversification across sectors, risk reduction through broad exposure, bull market outperformance relative to large caps, and attractive long-term growth potential, though with greater volatility during downturns. The volatility caveat matters. Small caps can fall significantly harder than large caps during market stress.
The Fed’s pivot toward easing in late 2025 changed the equation materially for small caps. Lower borrowing costs reduce interest expense, improve free cash flow, and make it cheaper for small companies to invest in growth, all of which flow through directly to earnings. The S&P 600 Small Cap index experienced 11 straight quarters of negative year-over-year earnings growth from 2022 to early 2025. That trend is finally beginning to reverse. The index returned to positive earnings growth in the second quarter of 2025. The turnaround is still relatively young.
9. Speculative and High-Risk Investments
9. Speculative and High-Risk Investments (Image Credits: Unsplash)
At the far end of the spectrum sit strategies built around maximum upside with a corresponding willingness to lose a significant portion, or all, of the invested capital. This category includes highly leveraged positions, options trading, pre-IPO shares, and concentrated bets on early-stage companies. The riskiest bonds are known as high-yield bonds or junk bonds. High-yield corporate bonds that are low rate and low quality are considered more risky because you have not just the interest rate risk, but the default risk as well.
With U.S. Investment Grade spreads near historical tights, investors may find more attractive valuations in U.S. High Yield Credit and securitized products. High yield fundamentals have remained solid, but index spreads are below 300 basis points, something that has occurred only 5% of the time since January 2000. This means there may be little cushion for unexpected defaults. Speculative investing is genuinely appropriate for a small portion of a portfolio when someone has a long time horizon, surplus capital, and a clear-eyed understanding of what they’re doing. It’s misapplied when it becomes the whole plan.
Risk tolerance isn’t fixed. It shifts with age, income, life events, and market experience. A portfolio that felt right five years ago may no longer reflect where you actually stand today. The most useful thing this spectrum offers isn’t a prescription, but a mirror worth looking into periodically.