
Money disagreements rarely start with the number itself. They usually start with an assumption one partner never said out loud and the other never thought to ask about. Financial advisors who spend their days sitting between couples at the kitchen table have noticed the same patterns over and over, and a handful of budgeting habits keep showing up as the difference between households that argue constantly and ones that mostly don't.
1. The 50/30/20 split as a shared reference point
1. The 50/30/20 split as a shared reference point (Image Credits: Unsplash)
One of the most commonly recommended frameworks divides after tax income into three simple buckets. Advisors often point couples toward the 50/30/20 budgeting rule, allocating 50% of income to household needs, 30% to wants like shopping and dining out, and 20% to savings or debt. The appeal isn’t precision, it’s that both partners are suddenly speaking the same language instead of arguing from different mental spreadsheets.
What makes this rule useful for reducing conflict is less about the exact percentages and more about the shared vocabulary it creates. The rule is just one way to organize a budget, and finding the right fit often means consulting a professional financial planner. Couples who adopt even a loose version of it tend to stop debating whether a purchase was reasonable and start checking it against an agreed category instead.
2. A recurring, scheduled money conversation
2. A recurring, scheduled money conversation (Image Credits: Pexels)
Advisors consistently point to the absence of routine check ins as a bigger problem than any single overspending incident. Many couples avoid talking about money because it feels awkward, but advisors say not budgeting together is one of the most overlooked financial red flags in marriage, since couples who don’t plan together often find themselves stressed about bills or unprepared for emergencies. The fix isn’t complicated, it’s just consistent.
A weekly or monthly sit down turns money from an emotional ambush into a scheduled task. Rather than only talking about finances when stressed about bills, a better strategy is setting a specific time each month to review recent spending, income, savings, bills, and investments, or aiming for quarterly sit-downs if monthly isn’t realistic. Couples who treat this like a standing appointment, not a crisis meeting, tend to catch small issues before they become arguments.
3. Personal "no questions asked" spending money
3. Personal "no questions asked" spending money (Image Credits: Pexels)
Even couples who share nearly everything financially benefit from carving out a little independence. One approach advisors recommend involves setting aside a certain amount of money for each partner to spend on whatever they want with no questions asked, giving the couple freedom to spend on themselves without guilt or fights. It sounds small, but it removes a huge source of daily friction.
The logic is straightforward once you see it in practice. Financial disagreements tend to escalate fastest when neither person can spend anything without an interrogation, so giving each partner even a small amount of discretionary money helps prevent that dynamic. A modest personal allowance, built into the budget rather than fought over after the fact, keeps small purchases from turning into referendums on trust.
4. Full transparency, not partial disclosure
4. Full transparency, not partial disclosure (Image Credits: Pexels)
Splitting the money conversation into separate silos, day to day spending here, investments over there, tends to backfire. Advisors note that people often split the money conversation between household budgets and investing, when in reality conversations should cover all things money, including spending habits, budgets, investments, and family spending history. Partial transparency creates blind spots, and blind spots eventually become arguments.
The opposite habit, hiding accounts or debt, tends to create the deepest damage. Some spouses open credit cards or maintain savings accounts without telling their partner, a pattern known as financial infidelity that advisors warn can quickly erode trust, since the truth usually comes out in the worst way. Advisors generally agree that full visibility into the numbers, even the uncomfortable ones, prevents far more conflict than it causes.
5. Shared or jointly reviewed accounts
5. Shared or jointly reviewed accounts (Image Credits: Pexels)
Whether or not a couple fully merges their finances, most advisors favor some level of joint visibility over a strict his and hers split. Most financial advisors give joint bank accounts a strong endorsement because it fosters openness and teamwork when couples share responsibility for household income. That doesn’t mean every dollar has to flow through one account, but it does mean neither partner should be guessing at the full picture.
There are real tradeoffs to consider, and advisors are upfront about them. Sharing every penny can also lead to secrets, distrust, and blame between partners, especially if they have different spending habits and personalities. The middle ground many advisors suggest is a joint account for shared expenses paired with individual accounts for personal spending, which keeps the transparency benefits without eliminating autonomy entirely.
6. Bringing in a professional together, not separately
6. Bringing in a professional together, not separately (Image Credits: Pexels)
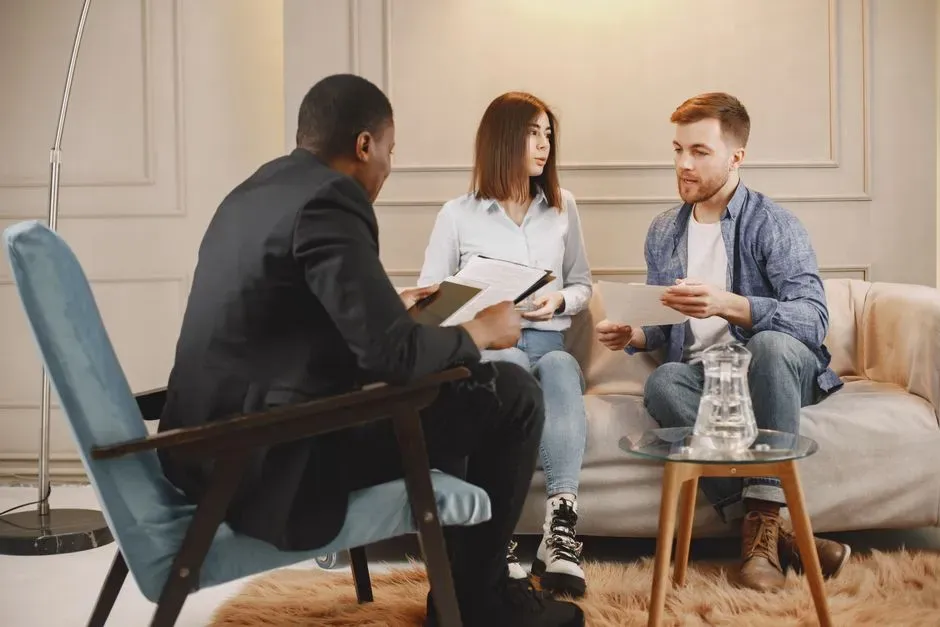
When couples do consult outside help, advisors say doing it as a pair matters more than people expect. Attending conversations with a lawyer, tax preparer, or financial advisor as a couple prevents misunderstandings and means either partner could step in and manage things alone if an emergency required it. One partner acting as the sole go between with a professional often recreates the exact power imbalance that causes arguments in the first place.
This habit also reinforces something advisors return to again and again: money fights are frequently about something other than the dollar amount. Marriage counselors consistently find that money arguments are often proxies for something bigger, differing views on security, trust, or what the relationship is actually building toward. A shared meeting with a neutral professional gives both partners the same information at the same time, which tends to defuse the sense that one person is managing the other.
None of these six habits require a finance background or a complicated spreadsheet. What they share is a simple mechanism: they replace assumptions with agreements. Couples who build these rules into their routine aren’t necessarily wealthier or more disciplined than everyone else, they’ve just removed most of the guesswork that turns ordinary spending decisions into arguments.