Ask around and you’ll find that vacation planning looks different in almost every household. Some families throw travel costs into their general spending and hope for the best, while others treat trip money as its own distinct category, tracked and protected the same way a mortgage payment or car insurance bill might be. That second approach has quietly become more common in recent years, driven partly by rising travel costs and partly by a broader shift toward intentional, categorized budgeting.
The reasons behind this habit are more practical than glamorous. It’s less about indulgence and more about avoiding the kind of financial stress that can follow an unplanned trip or a poorly timed credit card bill.
Rising travel costs make guesswork risky
Rising travel costs make guesswork risky (Image Credits: Unsplash)
Airfare, lodging, and dining prices have shifted noticeably over the past few years, and not always in predictable directions. Households that once budgeted loosely for travel have found that a vague estimate no longer covers the actual bill once taxes, resort fees, and baggage charges are added in. A dedicated fund forces a more realistic look at what a trip will actually cost before it happens, rather than after.
This matters because travel inflation doesn’t always move in step with general inflation. Some destinations see sharp seasonal price swings, while others hold steady, and a household that tracks vacation spending separately is better positioned to notice these patterns year over year. That awareness alone can shift when and where a family chooses to travel.
Separate funds reduce reliance on credit cards
Separate funds reduce reliance on credit cards (Image Credits: Pexels)
One of the more practical reasons households isolate vacation money is to avoid financing trips through credit card debt. Paying interest on a week at the beach can quietly double or triple the real cost of the trip if the balance lingers for months afterward. A dedicated fund, built gradually, sidesteps that problem entirely by ensuring the money exists before the trip does.
This is less about avoiding credit cards altogether and more about using them intentionally, for points or protections, while still having cash-equivalent funds ready to cover the bill in full. Families who’ve been burned by a slow-to-pay-off vacation balance tend to become strong believers in this separation. It’s a lesson usually learned once, not repeatedly.
Envelope-style budgeting brings clarity
Envelope-style budgeting brings clarity (Image Credits: Pexels)
The envelope budgeting method, whether done with literal cash or through digital sub-accounts, has seen a resurgence as households look for simpler ways to control discretionary spending. Vacation funds fit naturally into this system because travel is a category with a clear start and end date, unlike ongoing expenses like groceries or utilities. Setting aside a fixed amount each month toward a labeled “vacation” envelope makes the goal visible and tangible.
This visibility matters more than it might seem. When money sits in a general checking account, it’s easy to spend it on something else before a trip ever gets booked. A separate fund, even a virtual one inside a banking app, creates a small psychological barrier that discourages casual dipping into travel savings for unrelated purchases.
It protects the rest of the household budget
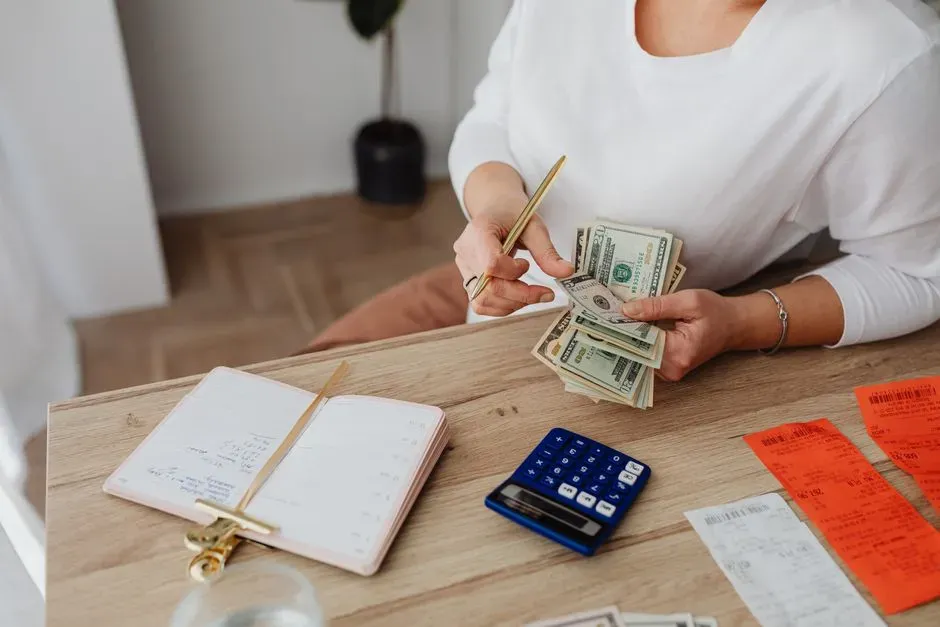
It protects the rest of the household budget (Image Credits: Pexels)
Vacations are, almost by definition, irregular expenses. They don’t show up every month like rent or a phone bill, which makes them easy to underestimate when building a broader financial plan. By carving out a dedicated fund, households prevent travel costs from bleeding into categories meant for groceries, utilities, or savings goals unrelated to leisure.
This separation also helps during the months when no trip is planned. Money set aside for vacations sits untouched and growing, rather than being folded into whatever spending happens to feel urgent that week. It keeps the rest of the budget cleaner and easier to track.
Multiple trips a year require more structure
Multiple trips a year require more structure (Image Credits: Unsplash)
Households that travel more than once annually, whether for a summer trip and a winter getaway, or frequent weekend excursions, tend to need more structure than a single lump sum can provide. A single vacation fund covering multiple trips throughout the year requires careful allocation so that an early trip doesn’t drain resources meant for a later one. Some families solve this by creating sub-funds within a larger travel budget, each earmarked for a specific trip.
This kind of layered budgeting takes more effort upfront but pays off in reduced stress later. It also allows for more honest trade-offs, like choosing a modest weekend trip in spring to preserve funds for a bigger trip in December. Without that structure, families often end up overspending early and scrambling later.
Kids and family trips change the calculus
Kids and family trips change the calculus (Image Credits: Pexels)
Traveling with children introduces cost variables that solo travelers or couples rarely face, from extra plane tickets to larger accommodations to activities geared toward younger travelers. Families with kids often find that vacation costs rise faster than expected as children grow older and their interests, and appetites, expand. A dedicated fund allows parents to plan further ahead, sometimes saving over twelve months for a single major family trip.
This approach also gives children a sense of anticipation and involvement, especially when families talk openly about saving toward a specific destination. Some parents use this as a teaching moment, showing kids how consistent saving over time turns into a real, tangible experience. It reframes vacation savings as a shared goal rather than a private financial chore.
Windfalls and bonuses get earmarked early
Windfalls and bonuses get earmarked early (Image Credits: Unsplash)
Tax refunds, work bonuses, and other irregular income are commonly funneled directly into vacation funds rather than absorbed into everyday spending. This works because these windfalls are already “extra” money, not part of the regular budget, so redirecting them toward travel doesn’t require cutting back elsewhere. Households that follow this pattern often find their vacation fund grows in visible jumps rather than slow monthly increments.
This method also reduces the temptation to spend a windfall impulsively on smaller, less meaningful purchases. Committing a bonus to a vacation fund the moment it arrives, before it sits in a checking account tempting other spending, is a simple but effective discipline. It turns an unpredictable financial event into progress toward something planned and intentional.
Interest-bearing accounts add a small bonus
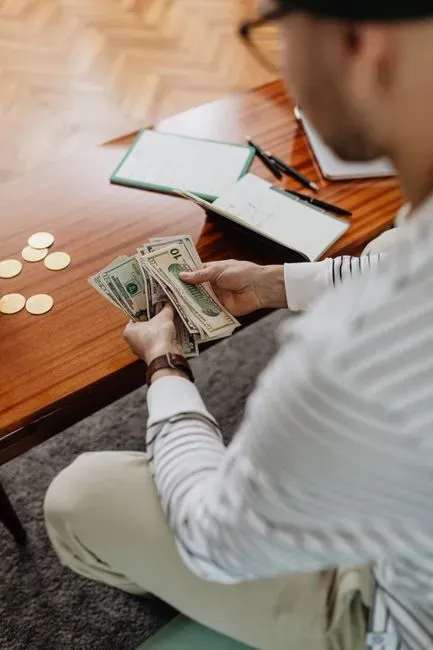
Interest-bearing accounts add a small bonus (Image Credits: Pexels)
Because vacation funds are typically saved for months before being spent, some households park them in high-yield savings accounts rather than a standard checking account. This doesn’t dramatically change the outcome, but it does mean the fund grows slightly on its own while waiting to be used. Given that many online savings accounts have offered noticeably higher interest rates over the past couple of years compared to the previous decade, this small addition has become more noticeable than it once was.
Households that are especially deliberate about this sometimes ladder their vacation savings across short-term certificates of deposit timed to mature right before a planned trip. This isn’t a strategy for everyone, since it requires knowing travel dates well in advance, but for predictable annual trips it can squeeze out a bit of extra value from money that would otherwise sit idle. It’s a small optimization, not a game changer, but it adds up over several years of consistent saving.
It supports better trip planning decisions
It supports better trip planning decisions (Image Credits: Unsplash)
Knowing exactly how much money is available for travel, separate from other financial obligations, tends to lead to more grounded planning decisions. Families with a clear vacation budget are less likely to book something impulsively that stretches finances thin, and more likely to compare options, timing flights or accommodations around what the fund can actually support. This often results in trips that feel less financially stressful both before and after they happen.
It also changes the emotional tone of trip planning. Instead of anxiety about whether a vacation is “affordable,” households with a dedicated fund can focus on where to go and what to do, since the financial question has already been answered in advance. That shift, from worrying about money to enjoying the planning process, is often cited as one of the most satisfying parts of this budgeting habit.